Eligible first-time buyers may be able to access help with down payment and closing costs through the county program.
Visit Richland County →
Columbia & Richland County
Buy local. Plan with the whole payment in view.
From Main Street to Northeast Columbia and Blythewood, the property address affects taxes, insurance, assistance eligibility, commute, and ultimately the monthly payment.
Local starting points
Resources worth exploring.
Programs change. Always confirm current funding, eligibility, income limits and participating-lender requirements before relying on assistance.
State programs may pair fixed-rate mortgage options with down payment assistance for eligible first-time, move-up and repeat buyers.
Explore SC Housing →Owner-occupied legal residences may qualify for South Carolina's 4% assessment ratio. Confirm eligibility and filing with the county.
Check county resources →A housing counselor can offer independent education on budgeting, readiness, credit and the homebuying process.
Find a counselor →
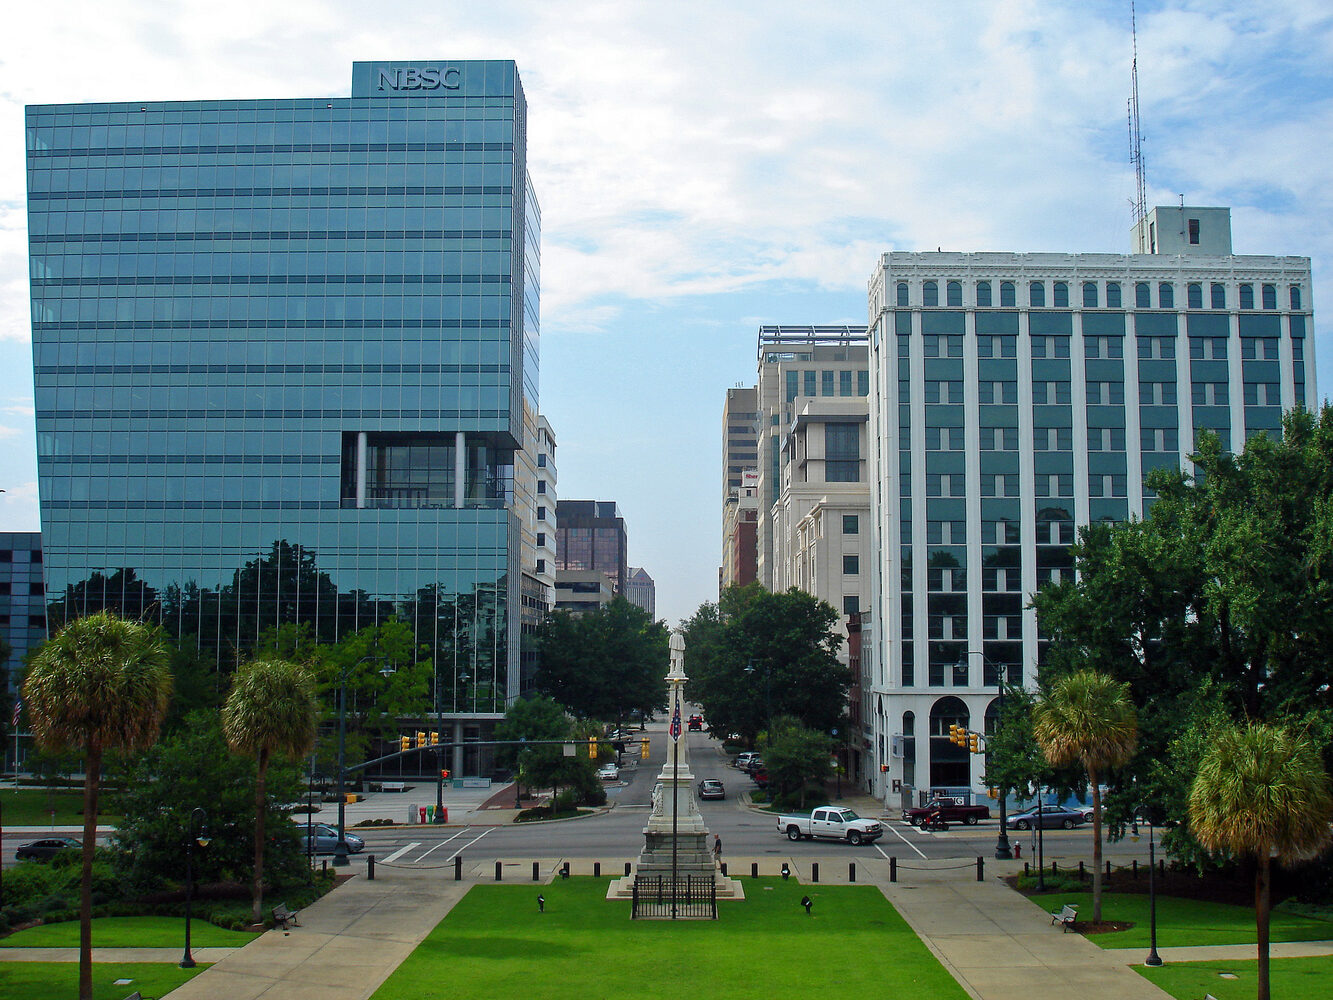
Main Street, Columbia
Local context belongs in the mortgage conversation.
Home price is only the headline. Taxes, insurance, association dues, property condition and assistance eligibility all shape the real payment.
Antonio brings the financing conversation back to the details you can verify—so you can compare homes and neighborhoods with a clearer understanding of the monthly cost.
Your local payment checklist
1
Property taxes
Estimate taxes for the specific address and intended occupancy, then verify rather than relying on a seller’s current bill.
2
Homeowners insurance
Get a property-specific quote early. Roof age, claims history and other factors can move the payment.
3
HOA and property condition
Include association dues and consider whether property condition could affect FHA appraisal requirements.
Found a home—or just choosing an area?
We can model the payment using the property details that matter.